12
months
Bay Views on Hayat Island, Mina Al Arab, Ras Al Khaimah is handed over and ready now; Property Finder’s project page shows completion on 31 August 2026. The full floor of twelve residences (9,364 sq ft) is offered as one transaction at AED 16,200,000, about AED 1,730 per sq ft; the residences are not sold individually. Indicative rents of AED 65,000 to 70,000 for a one-bedroom and about AED 110,000 for a two-bedroom imply roughly 4% gross on the floor before the studios are let and before service charges and other costs. Wynn’s 2027 opening does not guarantee higher returns.
The UAE has never had a casino. In September 2027 it gets its first: Wynn Al Marjan Island, a 70-storey resort on a 60-hectare island in Ras Al Khaimah. Beachfront apartments along the same coast are changing hands today at the prices we paid in 2022. This page shows why that gap exists, what our own unit has done since, and what could still go wrong.
Until Wynn's scheduled opening (September 2027). The window is defined by the calendar, not by us.
Price per sq ft: RAK figure is the Mina Al Arab / Hayat Island median asking price from our weekly RAK Waterfront Pulse (RAK publishes no open transaction registry); Dubai figure is a DLD transacted median. Asking runs above transacted, so the real gap is at least this wide. Dubai payment-plan and service-charge cells are typical ranges, not a single contract. Yields: RAK is measured on the 40% actually paid, Dubai on 100% paid; on full price RAK is 3.4% and Dubai wins that row.
The scorecard is deliberately unflattering to Ras Al Khaimah where it should be. Measured on the full price the yield is an unremarkable 3.4%; it is the 40/60 plan that turns the same rent into ~8.5% on cash, and a thin resale market is a real cost. Neither of those is why we bought. We bought for the three cells in the first column that Dubai cannot copy: less than half the entry price, half the buying cost, and a catalyst with a date on it.
Every number that made our 2022 purchase work, launch pricing, an interest-free plan, a buyer’s 2% transfer fee deferred to the final instalment rather than paid at purchase, a tenant from day one, is available again in September 2026 for a different reason: some owners need liquidity, and some are simply frightened. Neither reason changes what is being built 15 minutes up the coast.
Construction costs have also moved. Wynn's own budget rose by US$600m this year on materials and shipping. New launches along the coast cannot be delivered at 2022 cost, which puts a floor under replacement value. It does not put a floor under resale demand, which is the part the conflict has hit.
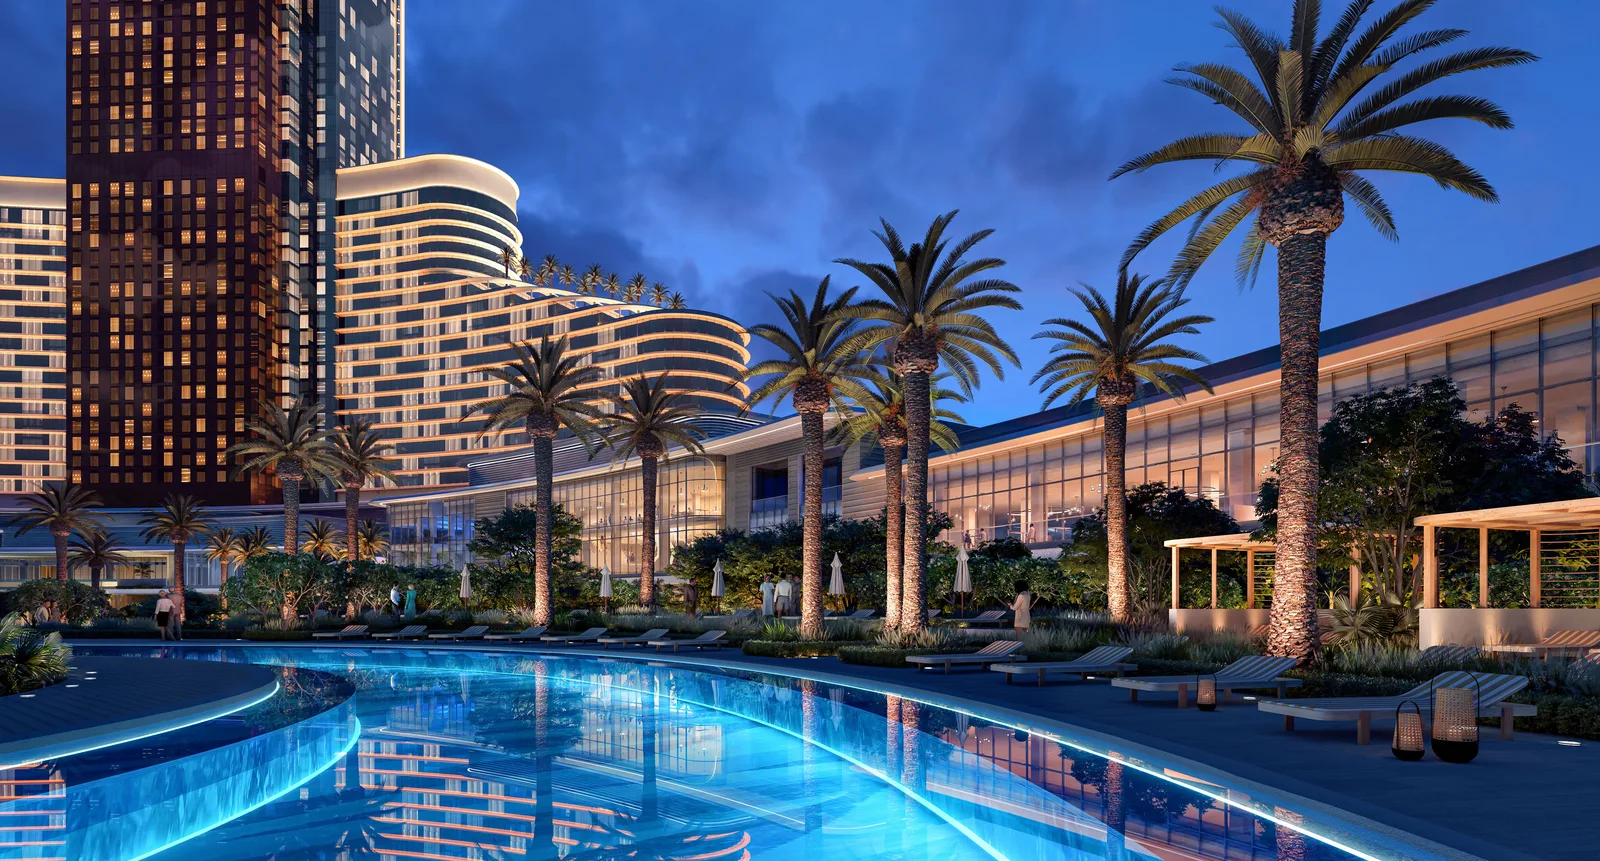
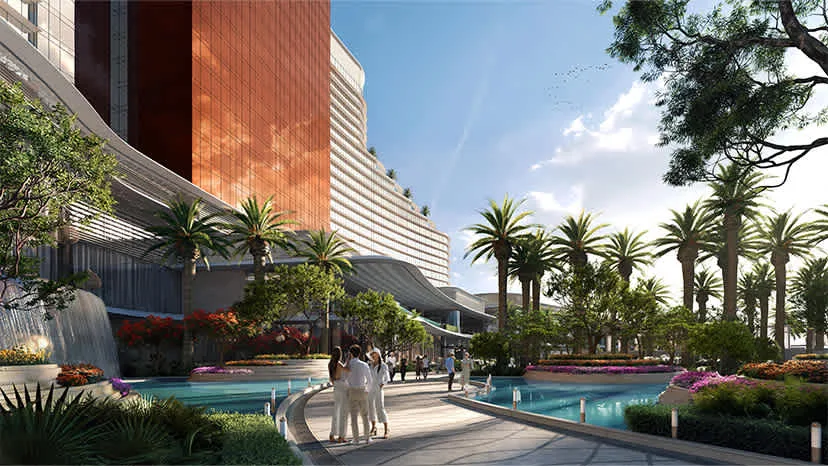
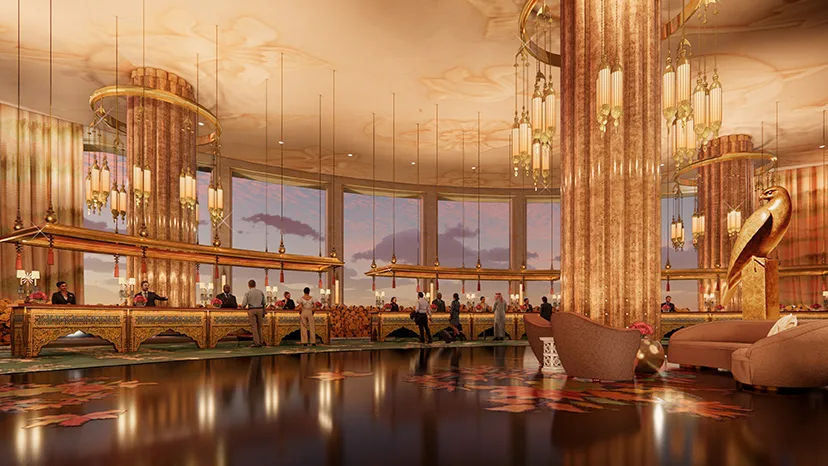
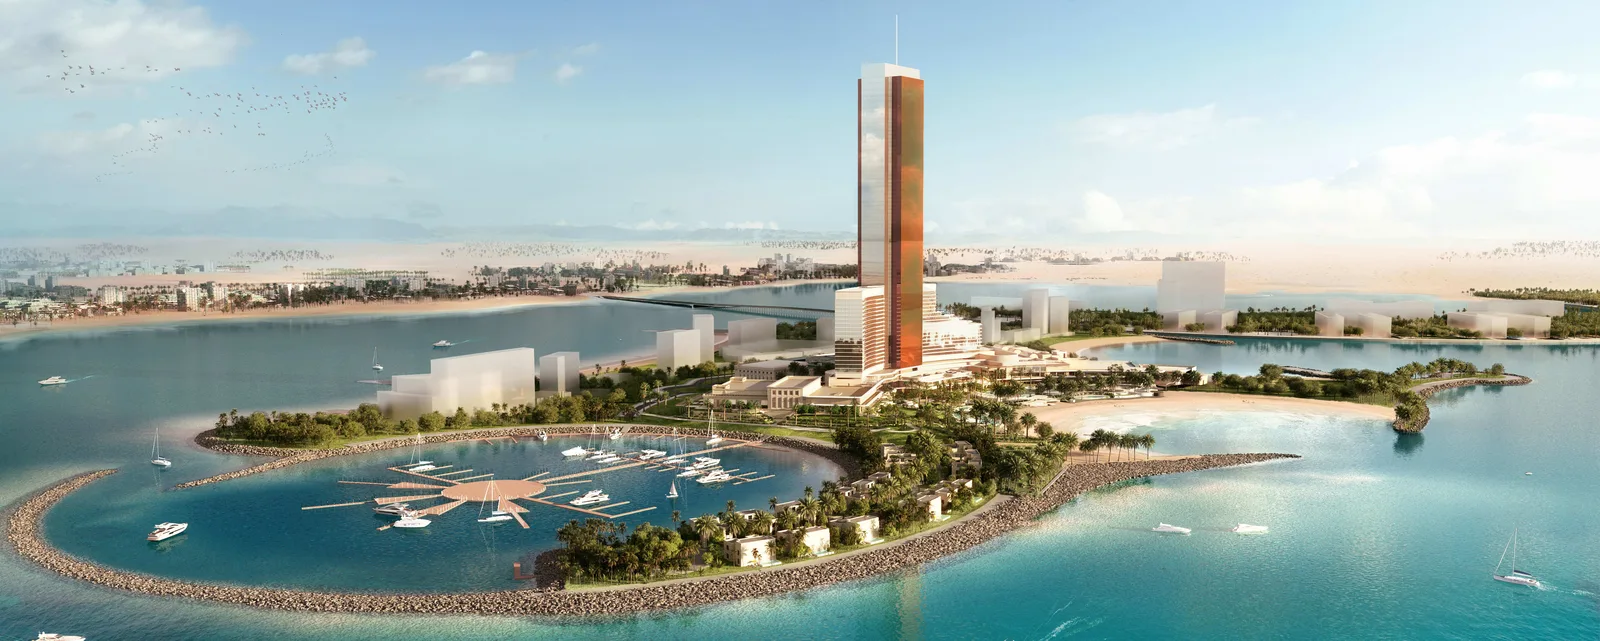
Wynn Resorts holds the UAE's first and, so far, only commercial gaming licence. The company built the Wynn and Encore in Las Vegas, Wynn Macau and Wynn Palace in Cotai. Wynn Al Marjan Island is its first resort outside the United States and Macau, in a country of about 10 million residents and more than 20 million annual visitors that has no other casino.
The clean version of the story is "casinos make property prices go up". The true version is narrower and more useful. A casino that is one of many in a crowded region does nothing for housing; Atlantic City is the counter-example everyone forgets. A casino that is a nation's first, run by a top-tier operator, in a wealthy market with no alternative, creates a destination that did not exist. Singapore's waterfront re-rated over the five years after Marina Bay Sands opened in 2010. Al Marjan fits that second pattern: one licence, one operator, 400 million people within a four-hour flight, and a beachfront of fixed length beside the island Wynn will fill. Mina Al Arab is the nearest established beachfront community to it that is not on the island, and one of the few gated communities in the emirate where residents walk from their door onto a private beach. That is exactly why it is cheaper: Al Marjan luxury now asks a reported AED 2,500–4,000 per sq ft, Mina Al Arab a fraction of that (scorecard above).
Two cautions. Singapore's re-rating coincided with a global recovery, and it took years, not months. Nobody should buy here expecting the September 2027 ribbon-cutting to move prices the following quarter.
Bayut and Cavendish Maxwell figures as reported by Omnia Capital (April 2026) and Arabian Business. Prices rose while volumes fell: fewer launches, not weaker demand. Treat bullish 2030 forecasts of AED 8,000+ per sq ft circulating online as marketing, not a base case.
| Item | Amount (AED) | What it means |
|---|---|---|
| Purchase price, Dec 2022 | 1,100,000 | Launch pricing, before the Wynn effect was visible. Contract price. |
| Paid by handover (40%) | 440,000 | The other 60% is spread over 5 years after handover, interest-free. The buyer’s 2% share of the 4% RAK transfer fee (2% buyer + 2% seller, the same structure as Dubai) is not paid at purchase; it falls due with the final instalment. |
| Rent from handover | 50,000 / yr | Tenant in place from day one; RAK 1-beds on our desk let for AED 50,000–70,000. ~11% gross on the cash paid (4.5% if measured on full price). |
| Service charge (12 × 825 sq ft) | −9,900 / yr | Beachfront amenities. Heavy at 20% of rent; shrinks only as rent rises. |
| Net rent in hand | ~37,600 / yr | After service charge and a 5% vacancy allowance. ~8.5% net on the cash paid, 3.4% net on the full price. |
| Resale, 2025 (several units) gain on price / on cash paid | +43% / +80–100% | Realised. Measured on the cash actually paid in, 42% at handover and about 54% a year later, the gain was +80% to +100%. That is the number that matters, because the unpaid balance was never our money. |
For scale: the most-traded Dubai 1-bed markets of the same years, Business Bay (2022) and JVC (2023), returned 5–7% net yields on registered Ejari rents and 34–55% unrealised gains with 100% of the price paid. Higher yield, lower leverage, no single catalyst ahead.
Assume a Mina Al Arab beachfront 1-bed bought today at a 2022-level price of AED 1.1M, taking over the original plan: 40% paid on transfer, then 12% of the price a year until 2031, with the buyer’s 2% share of the transfer fee due at the final instalment. Held to the end of 2028, roughly 15 months after Wynn opens, the buyer will have paid in about AED 704,000 and still owe 36%. Returns below are measured on that AED 704,000 actually paid, not on the full price. Rows are the rent achieved; columns are where the price lands; net rent deducts service charge and 5% vacancy.
The honest summary of that grid: if the casino does nothing for the island, a buyer at today's prices earns a savings-account return, about 3% a year, on a beachfront asset while funding the instalment gap. If it does what first-in-country resorts have done elsewhere, the same buyer earns 23–44% a year on the money actually put in, because the developer is financing the rest at zero interest. That asymmetry is the argument, not a promise of the bottom-right cell.
Most pages about RAK lead with the casino. Here it is the seventh item on the list, not the first.
For an apartment in RAK, direct beach access inside a gated community is rare unless you are on Al Marjan Island itself. Mina Al Arab has it, at a fraction of Al Marjan pricing, with the Anantara and the InterContinental as neighbours. This does not depend on any opening date.
40% gets you the keys; the developer carries 60% over five years at no interest. No bank, no valuation, no rate risk. It is why a 4.5% gross rent becomes an 11% gross return on cash, and why a 43% price rise became +80–100% for us.
The transfer fee is the same 4% of value in both emirates — 2% from the buyer and 2% from the seller — per RAK Municipality and the Dubai Land Department. What this plan changes is when the buyer’s 2% is paid: not at purchase, but with the final instalment. Ras Al Khaimah is cheaper on the fixed fees (AED 200 deed + AED 200 plan against Dubai’s AED 250 deed plus map, knowledge, innovation and trustee fees), not on the headline rate.
Our unit let at AED 50,000 on handover with no void. Mina Al Arab 1-beds on our desk now let for AED 50,000–70,000. In our experience rents here have risen roughly 10–15% a year since 2022, from a base low enough that they are still affordable to the staff Wynn will employ.
Mina Al Arab has been delivering since 2006: two five-star resorts, retail, a marina, schools within reach. Buyers here are not funding infrastructure that may or may not arrive; they are buying into a place that already works.
The conflict, not the fundamentals, has put units back on the market at launch pricing. RAK prices rose 21% in 2025 and Al Marjan luxury 39%; the current discount is a reversal of sentiment, not of the numbers underneath it. That is the definition of a window.
Topped out, licensed, dated. A US$5bn+ integrated resort by the operator behind Las Vegas and Macau's flagships, 15 minutes from your door, in a country with no competing venue. Everything above holds without it; with it, the middle and right columns of the return grid come into play.
Cavendish Maxwell expects about 8,400 new homes in RAK across 2026–2028, with 5,200 of them in 2028. Rents on ordinary units will be capped by that pipeline. Direct beach access inside a gate, in a finished community, is the defence: buy the frontage, not the pipeline.
Wynn has already moved once, from March to September 2027, and added US$600m to its budget. A further slip pushes every rent and price assumption on this page back by the same number of months.
The discount exists because of the conflict. If it deepens, the discount widens before it closes. This is a position for money that can wait until 2028, not for money that might be needed in 2027.
RAK trades a fraction of Dubai's volume. Exits take longer and gap wider. Our own 43% exits were achieved in a rising market; plan the exit at purchase, and prefer units the holiday-let operators want.
AED 12 per sq ft on a 50,000 rent is heavy. It shrinks as a share only if rent rises. Check the approved budget before buying; beachfront amenities do not get cheaper.
Mina Al Arab is a 15-minute drive from Wynn, not a walk. Units on Al Marjan will capture the first and largest re-rating; Mina Al Arab captures the spill-over, from a much lower entry price, with hotels, retail and a finished community in place, and with something Al Marjan's open-access towers cannot offer: a gated community with its own residents' beach.
A 60% post-handover plan costs 12% of the price a year, roughly AED 132,000 on a 1.1M unit, until 2031. Rent of 50,000 covers less than half. Buyers must fund the gap; the plan is the leverage behind every cash-on-cash figure on this page, and leverage cuts both ways.
September 2027, per Wynn Resorts. The date moved from March 2027 after a construction pause in early 2026, and the budget rose by about US$600 million to roughly US$5.7 billion. The 70-storey tower is already topped out.
RAK wins on entry price (Mina Al Arab asks about a third, and Al Marjan Island about half, of Dubai Marina's price per sq ft), the same 2% buyer + 2% seller = 4% transfer fee as Dubai but lower fixed fees, lower service charges, long post-handover payment plans, and one dated catalyst. Mina Al Arab adds something Al Marjan's towers cannot: a gated community with its own residents' beach. Dubai wins on rental yield today and on liquidity. Most of our clients hold both; see the two-pillar guide.
Both emirates charge the same headline transfer fee. RAK Municipality’s Real Estate Sale Contract service card states that “the seller and buyer each pay 2% of the market value of the property” — 2% buyer + 2% seller = 4%, the same structure as Dubai, where the Dubai Land Department likewise charges 2% from each side. The widely repeated “RAK is 2%, Dubai is 4%” comparison sets the buyer’s half in RAK against the combined figure in Dubai. Ras Al Khaimah is genuinely cheaper on the fixed fees: AED 200 for the title deed and AED 200 for the plan, against Dubai’s AED 250 title deed plus map, knowledge, innovation and trustee or registrar fees. Source: RAK Municipality Real Estate Sale Contract service card (ZL13), fetched 14 September 2026. On our Mina Al Arab contract the buyer’s half is not paid upfront: it falls due with the final instalment of the post-handover plan.
Our 825 sq ft Mina Al Arab unit (RAK Properties) is rented at AED 50,000 a year (RAK 1-beds on our desk let for AED 50,000–70,000): about 11% gross and ~8.5% net on the 40% cash actually paid under the 40/60 plan, after the AED 12 per sq ft service charge and a 5% vacancy allowance (3.4% net if you measure it on the full price). The 2025 resales at +43% on price were +80% to +100% on the cash actually paid in.
The period between now and September 2027 in which beachfront resale units along the RAK coast, in communities such as Mina Al Arab, are offered at or near 2022 launch pricing, because the early-2026 conflict pushed sellers to list. The catalyst has not happened yet; that is the whole argument.
Supply of about 8,400 homes across 2026–2028, a further Wynn delay, unresolved geopolitics, a thin resale market, a 15-minute drive to Wynn rather than an address on the island, a service charge near 20% of rent, and negative carry on a 60% post-handover plan. Buy direct beach frontage inside a gated community, plan the exit at purchase, and use money that can wait until 2028.
Yes. Non-UAE nationals can buy freehold in RAK's designated investment zones, including Al Marjan Island, Mina Al Arab and Al Hamra Village.
| Measure | Figure |
|---|---|
| Full floor of twelve residences, one transaction | AED 16,200,000 — 9,364 sq ft, about AED 1,730 per sq ft; not sold as individual units |
| Indicative annual rent | One-bedrooms AED 65,000 to AED 70,000; two-bedrooms about AED 110,000; studios confirmed on request |
| Gross yield on price | About 4% from the nine one- and two-bedrooms alone (roughly AED 720,000 to 750,000 a year on AED 16,200,000), before the three studios are let, and before service charge, vacancy and management |
| Service charge | Approximately AED 12 per sq ft per year (about AED 112,000 a year on the 9,364 sq ft floor) |
| Status | Handed over, ready now; completion 31 August 2026 per Property Finder |
Sources: Property Finder, RAK Properties — Bayviews project page and Wynn Resorts’ Q2 2026 earnings release, 4 August 2026, both fetched 14 September 2026. Prices and rents are Sofia Sands Realty asking figures from our own unit records, confirmed in writing before any commitment.
The number above is a gross yield measured on price: the annual rent divided by the purchase price, before any cost. On the full floor at AED 16,200,000, the six one-bedrooms letting at AED 65,000 to AED 70,000 a year and the three two-bedrooms at about AED 110,000 come to roughly AED 720,000 to 750,000 a year — about 4% gross before the three studios are let. That is the honest arithmetic for this building, and it is lower than the 7% and 8% numbers advertised elsewhere for Ras Al Khaimah.
What comes off it before the money is yours: the service charge, approximately AED 12 per square foot a year — about AED 112,000 a year on the 9,364 sq ft floor; any vacancy between tenancies; letting and management fees if you use an agent; and maintenance. We do not publish a single net figure, because yours depends on how you let it and who runs it. Ask for the building’s service-charge budget and model it yourself — we will send it.
Note the difference between this and the cash-on-cash figures further down this page. Those are returns on the 40% of the price we had actually paid under a post-handover plan on our own 2022 unit, not yields on price, and they are not Bay Views figures. Both are labelled wherever they appear.
Ras Al Khaimah is an emirate of the United Arab Emirates, and foreigners can buy freehold in its designated areas. Our stock sits in Mina Al Arab, a RAK Properties community on the coast; Hayat Island is an island inside it. Al Marjan Island — where Wynn Al Marjan Island is being built for a 2027 opening — is a separate island roughly a 12 to 15 minute drive away, by our own measurement. Bay Views is on Hayat Island, not on Al Marjan Island.
For context on the resort itself, including what we could not verify, see Ready RAK investment alternatives. For the community, the sourced price-per-square-foot context and what is complete versus still selling, see Bay Views investment numbers. Anantara Ras Al Khaimah Resort and InterContinental Ras Al Khaimah Resort & Spa are listed as operating in Mina Al Arab on RAK Properties’ hospitality page, fetched 14 September 2026.
Bay Views is handed over, so this is not a brochure decision. Twelve residences on floor 9 — three studios, six one-bedrooms and three two-bedrooms, 9,364 sq ft in total — are sold together as one lot at AED 16,200,000, about AED 1,730 per sq ft. The residences are not sold individually. The lobby is on floor 9, and from floor 5 upward the sea view clears the V-shaped building in front.
We will send the unit list, the rent achieved, the service-charge budget and the fee split in writing, then arrange a viewing. Ask for the ready Bay Views numbers on WhatsApp, or see the Bay Views page and every unit on our desk.
Gross yield is the annual rent divided by the purchase price, before any cost is deducted. At Bay Views the full floor is bought at AED 16,200,000; the six one-bedrooms let at AED 65,000 to AED 70,000 a year and the three two-bedrooms at about AED 110,000 give roughly 4% gross on price before the three studios are let. It is measured on price, not on the cash paid under a payment plan, and it is not the amount that reaches your account.
The service charge first: approximately AED 12 per square foot a year on our Ras Al Khaimah stock, about AED 112,000 a year on the 9,364 sq ft floor. Then any vacancy between tenancies, letting and management fees if you use an agent, and maintenance. We publish the gross figure and the service charge separately so you can net it yourself, and we send the building's service-charge budget on request rather than quoting a single net number.
No, and we do not claim it. Wynn Al Marjan Island opens in 2027 according to Wynn Resorts' own earnings release of 4 August 2026; it is not open today, the date has already moved once, and Hayat Island is a 12 to 15 minute drive away rather than on the island. A dated catalyst is a reason to look, not a forecast. Resale liquidity in Ras Al Khaimah is also thinner than in Dubai.
We are buying alongside our clients. Sofia Sands Realty currently has access to a short list of beachfront resale units in RAK Properties' Mina Al Arab community, a 15-minute drive from Wynn, at or near launch pricing, most with the original post-handover plans intact. We share the registered transaction record of every unit before you commit.
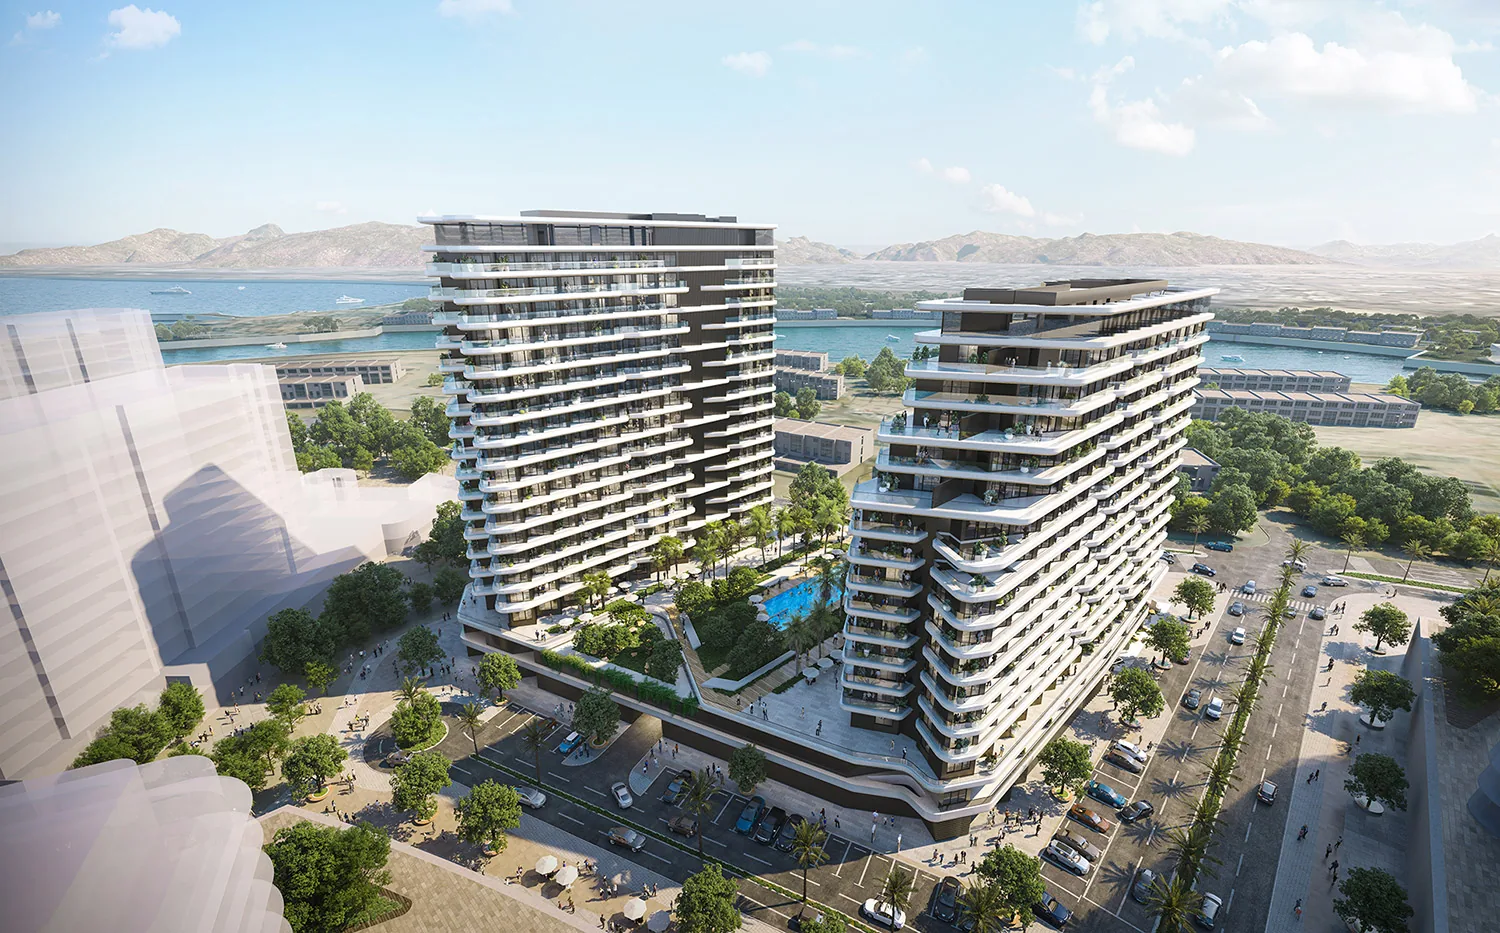
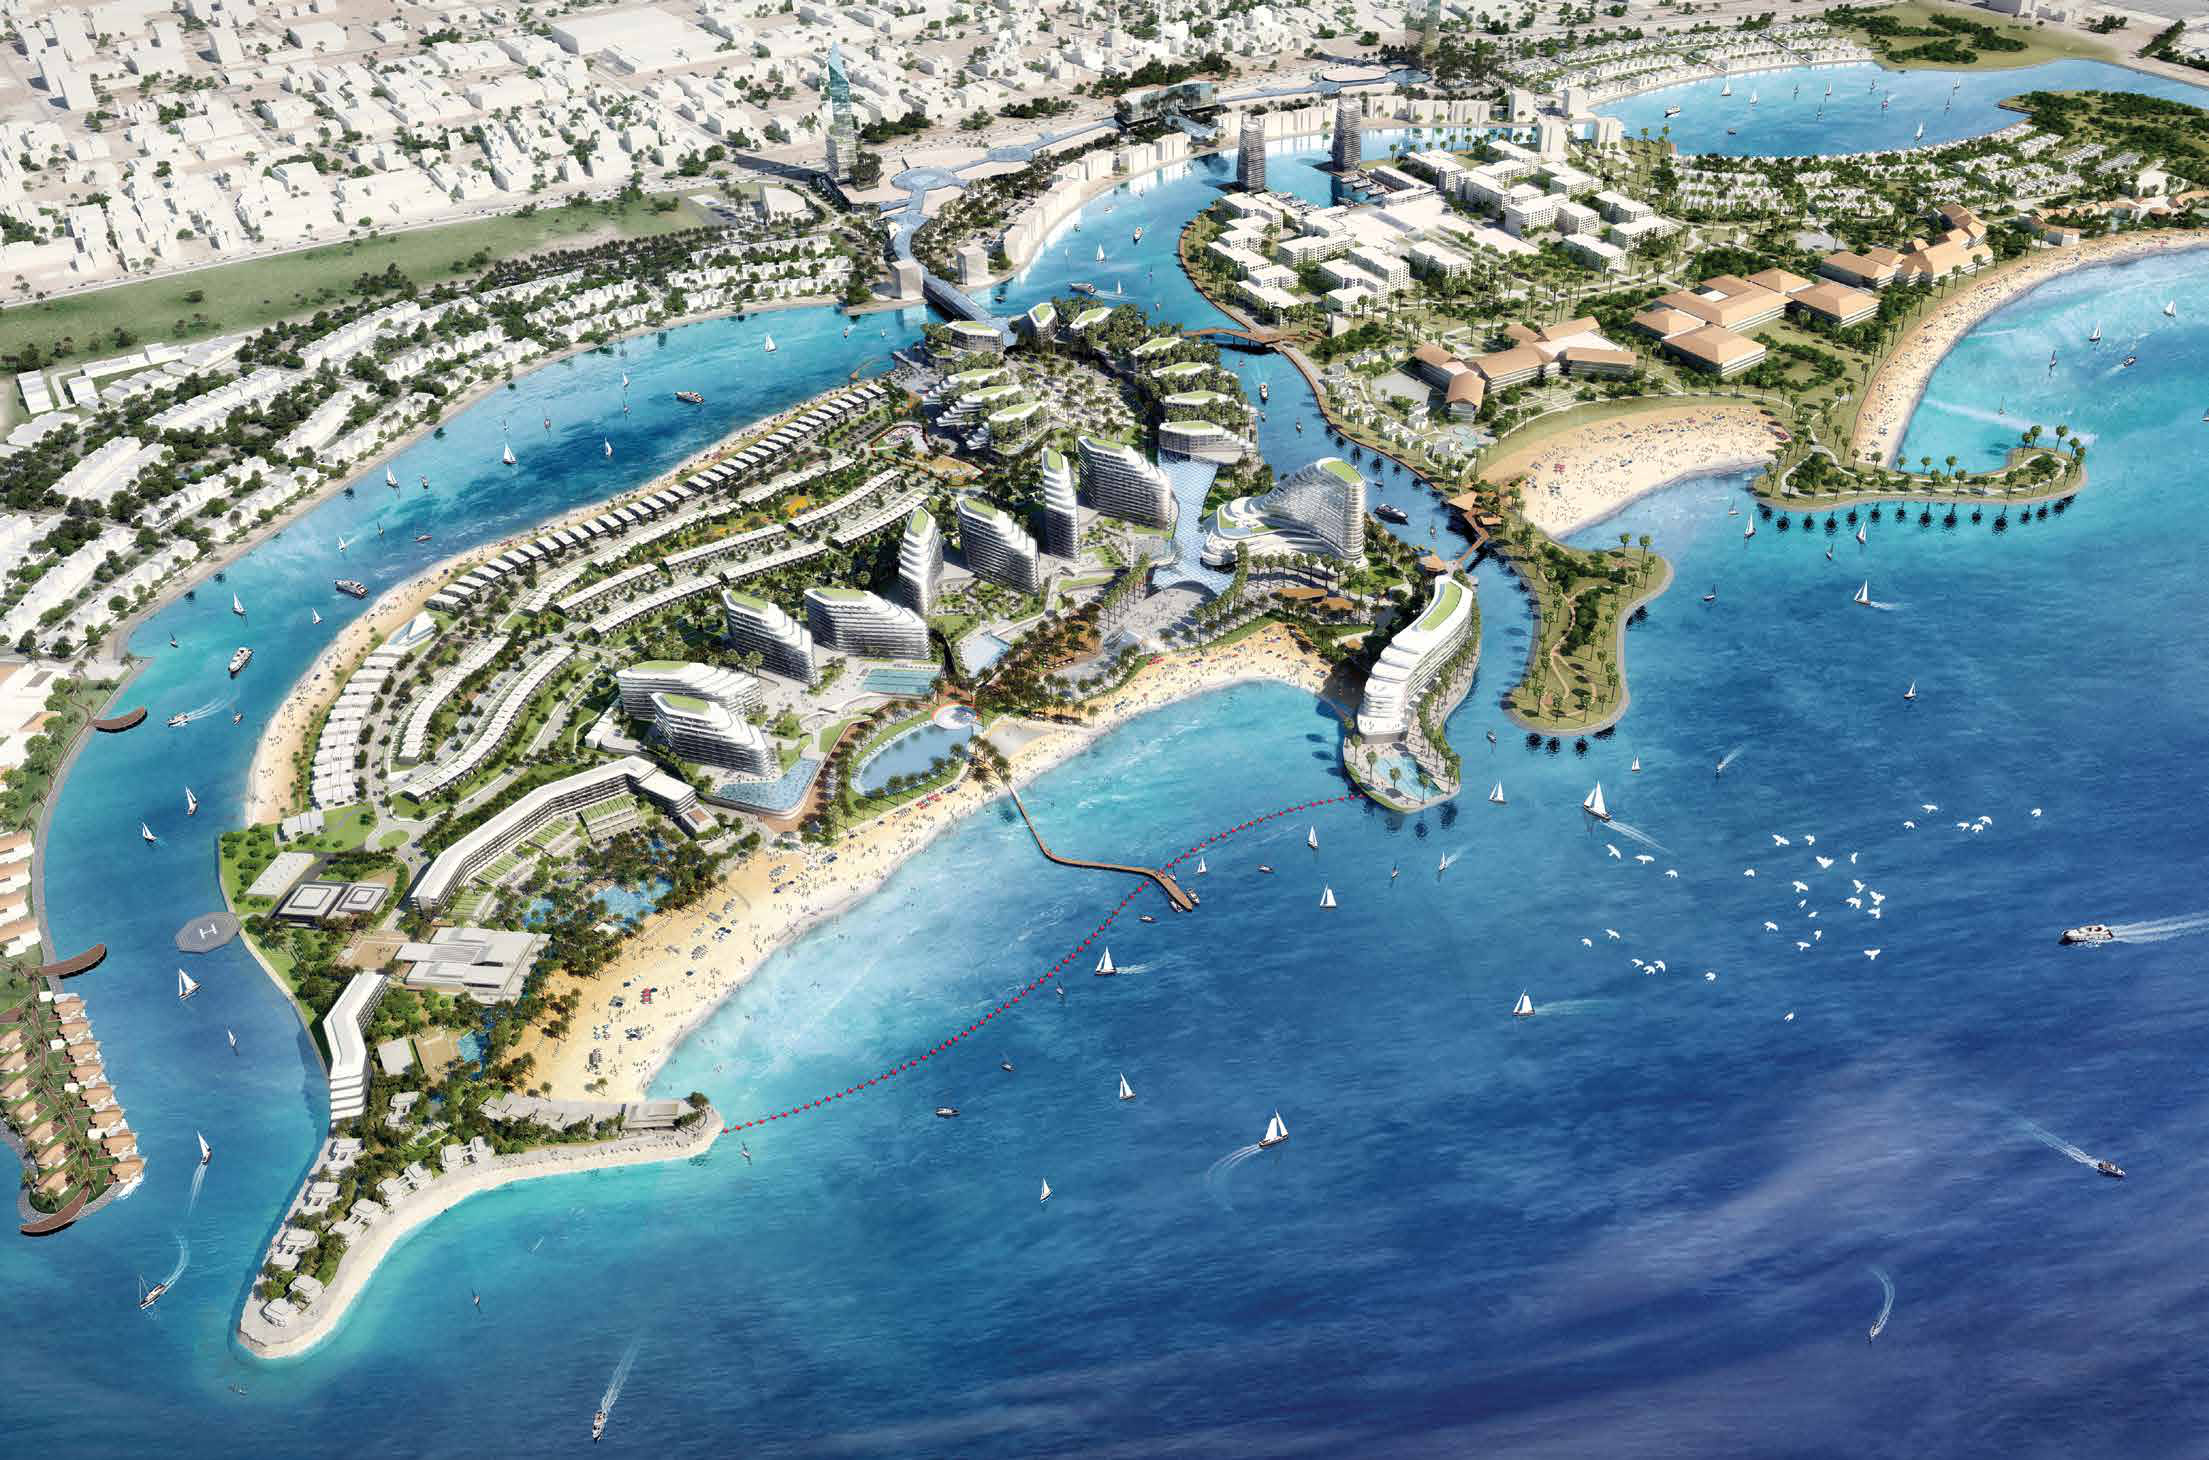
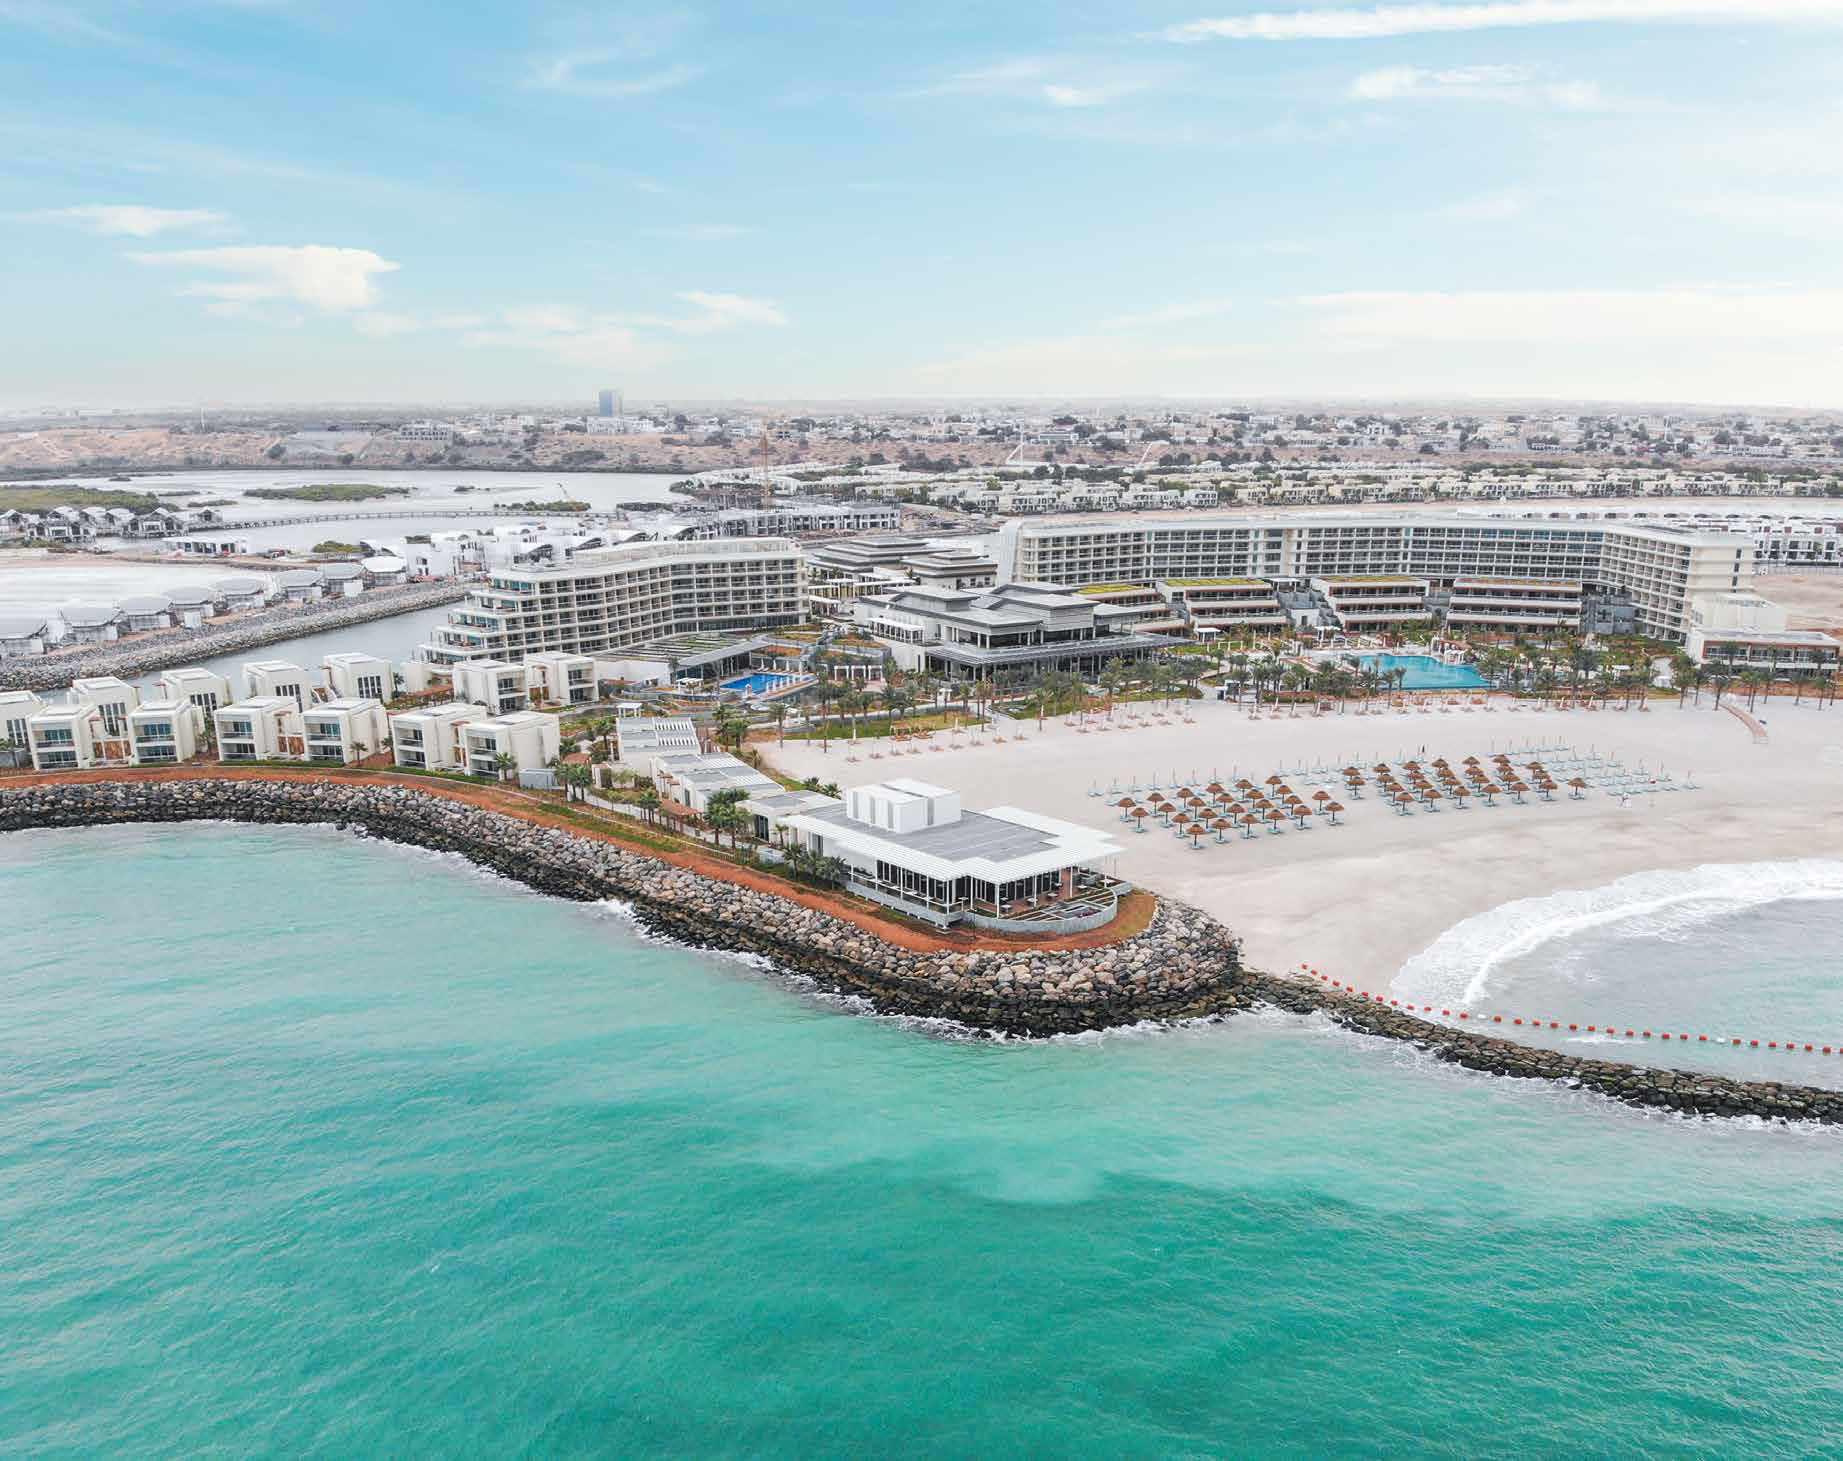
Photos and renders © RAK Properties. These are RAK Properties homes on Hayat Island, inside the same Mina Al Arab community as our own unit and a 15-minute drive from Wynn; the resale units in this note are shared on request, not listed publicly.