Quick answer · last checked 12 November 2026
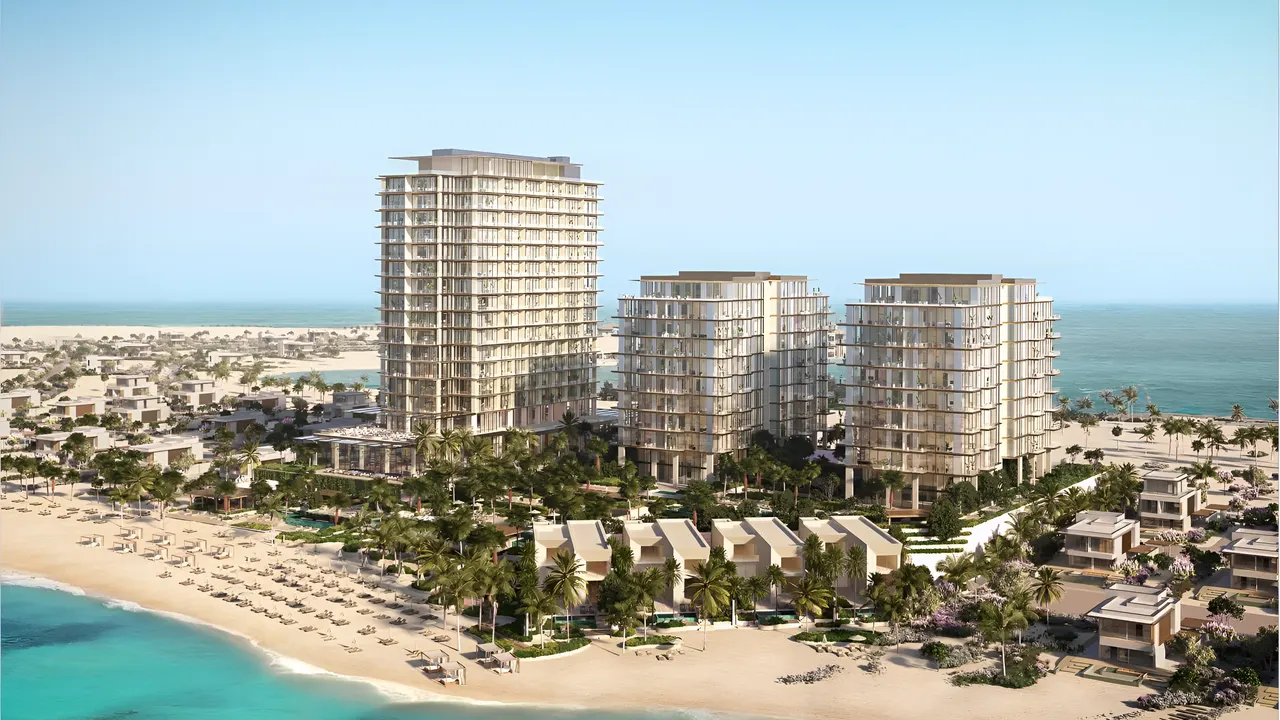
No evidence-backed short-term rental yield near Wynn can yet be quoted as a post-opening result. We would underwrite Ras Al Khaimah against long-term rent, then test holiday-let costs separately. The UAE Federal Tax Authority framework, checked October 2026, confirms no annual property tax; that does not remove operating expenses.Prefer to ask? Sofia answers on WhatsApp →
We test Wynn-related expectations against income a buyer can underwrite today, using a ready full-floor instruction, a clear account of costs and a long-term letting fallback.
What short-term rental yield near Wynn can we realistically underwrite?
For a Ras Al Khaimah purchase near Wynn, we would underwrite long-term letting first and treat holiday-let income as unproven. A purchase price and an operator presentation may be on the desk, yet neither explains what reaches the owner's bank account. That missing calculation matters more to the buying decision than the most attractive nightly rate.
Wynn Al Marjan Island is scheduled to open in September 2027, Wynn Resorts SEC filing / earnings release, 4 Aug 2026. We track that timetable through Wynn Resorts investor updates and our Wynn Al Marjan Island tracker. A scheduled opening tells us nothing about achieved apartment income after opening. We would reject a valuation that treats the future resort's demand as already measured.
Why are there no achieved post-opening operator figures?
Ras Al Khaimah operators cannot report achieved Wynn post-opening performance before Wynn opens. Existing holiday-let accounts can still help us assess comparable accommodation under current conditions, but that is a different test. We ask operators to keep historical accounts separate from forward bookings and forecasts. Folding them into an annual income line hides where the evidence ends.
We would request owner statements for comparable buildings, with identifying details removed where necessary, alongside the booking ledger and expense reconciliation. The occupancy calculation also needs scrutiny: it should explain how owner stays, maintenance closures and cancellations are treated. A rate without its denominator does not answer the investment question.
Our position is conservative: buy only if the alternative letting case and the cost of holding the property are acceptable. Verified operating results could change our view; a more ambitious presentation cannot. Long-term rent remains an underwriting reference, not a guaranteed minimum payment or protection against vacancy.

How should occupancy and nightly rate become a yield calculation?
We calculate holiday-let yield from collected accommodation income after operating expenses, divided by the buyer's complete invested capital. Headline booking revenue is the starting point, not the return. At the quotation desk, we ask the operator to show how that revenue becomes an owner payout before discussing the projected yield.
Start with nights genuinely available for guests. Remove owner occupation and planned closures explicitly rather than burying them in an occupancy assumption. Multiply available nights by evidenced occupancy to establish occupied nights, then apply the realised average nightly rate. Here, realised means after the discounts and refunds that affect accommodation receipts. The calculation must also state how it treats platform deductions.
We have left out an occupancy percentage and average daily rate because neither has a verified property-specific operating series behind it. An empty input is more useful than a plausible-looking assumption that quietly determines whether the buyer proceeds.
Which deductions belong between revenue and owner income?
Owner income must account for the operator contract, building bills and the cost of keeping accommodation guest-ready. We ask whether the operator's fee applies before or after booking-platform deductions. We also establish who bears cleaning shortfalls, utilities, linen replacement, call-outs and refunds. An identical fee label can produce a different amount in the owner's account.
| Calculation stage | Evidence to request | Common underwriting error |
|---|---|---|
| Available and occupied nights | Calendar reconciled to booking records | Excluding closed nights without disclosure |
| Collected accommodation income | Receipts after discounts and refunds | Using advertised nightly rates |
| Owner operating income | Contract and itemised operating ledger | Omitting owner-paid bills |
| Return on invested capital | Purchase and establishment cost schedule | Using purchase price alone |
We keep financing separate so the unlevered property return stays visible, then calculate the cash remaining after debt payments. We also require a replacement reserve. Furniture wears out: that is an economic expense even when no replacement appears in the current month's statement.
Which RAK location and apartment type make the strongest rental case?
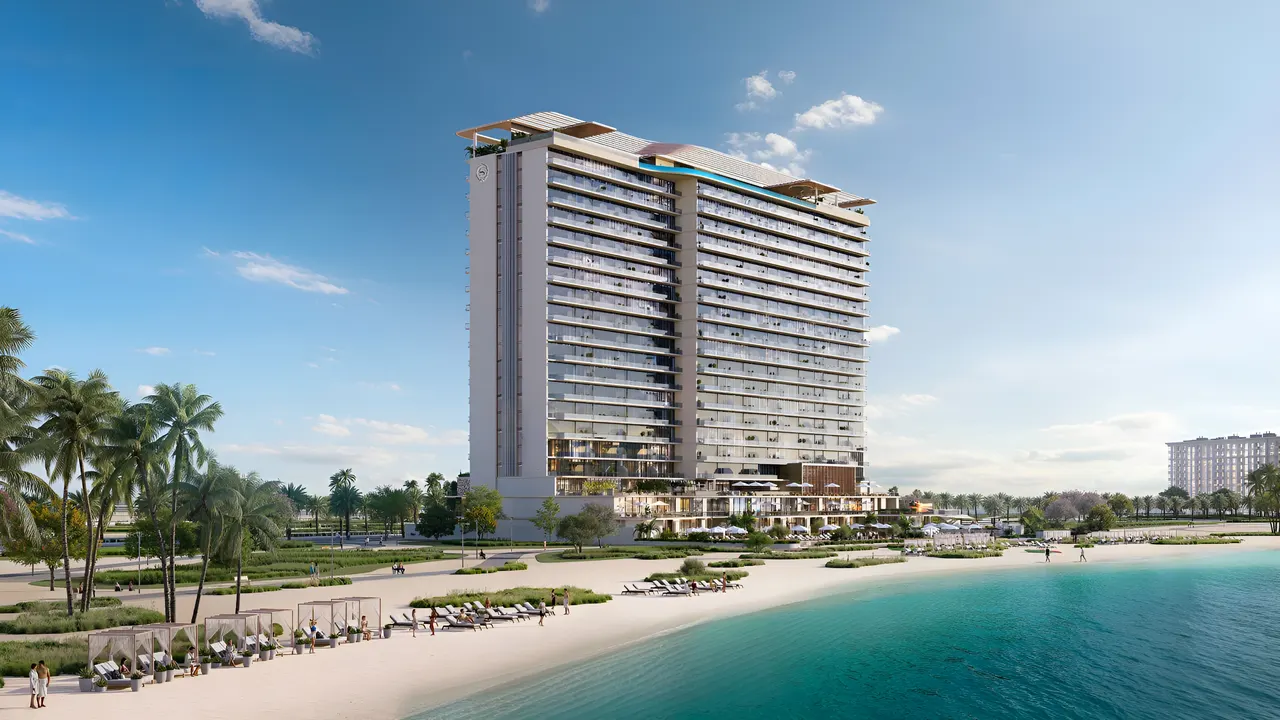
The strongest rental case is where purchase cost and achievable owner income work together; it is not automatically the property closest to Wynn. We would compare Al Marjan Island, Mina Al Arab including Hayat Island, and Al Hamra using the same expense definitions. A different postcode is no reason to lower the standard of evidence.
Our Ras Al Khaimah investment guide sets out the broader context, but we keep the viewing brief specific. We check the actual route to the resort and how guests reach and enter the building. A map pin cannot tell us whether a late arrival will find the entrance or whether the operator can resolve a lost access card.
Before treating an apartment as holiday-let stock, we ask the building manager to explain guest access. We would not proceed on proximity alone if that answer remained unclear, however persuasive the location looked on a map.
Do studios, one-bedroom or two-bedroom apartments produce better returns?
We compare apartment types by evidenced owner income against all-in cost; bedroom count alone does not establish a yield ranking. With a studio, we test whether the proposed guest profile suits the layout and storage. With a larger apartment, we check whether extra sleeping capacity earns enough additional receipts to cover cleaning, furnishing and wear.
The operator's comparable accommodation should have the same practical capacity. We would not accept a building-wide average in its place. Nor does a sofa bed in a presentation establish permitted guest capacity or genuine booking demand. We would obtain the applicable building and operating requirements before furnishing around that assumption.
Ready accommodation lets us inspect access and physical condition now. An off-plan rental case must account separately for completion, handover and guest-readiness before income starts. We would not compare a future annual revenue forecast with a ready property's current rent without showing that timing difference. Whichever route the buyer takes, building-specific evidence carries more weight than a general claim about which apartment size investors prefer.
What does the Wynn effect actually prove about rents and prices?
The Wynn effect supports a case for future demand in Ras Al Khaimah, but proves no individual apartment's future occupancy, nightly rate or net yield. We assess sale values separately from rents. A rising purchase price can make the income calculation less attractive even as the location draws more attention; interest in the resort does not resolve that tension.
Apartment prices rose 6.5% year on year, while apartment rents rose 7% year on year, Cavendish Maxwell H1 2026. Yet the latest quarter recorded apartment prices down 0.7% and apartment rents down 1.4%, Cavendish Maxwell H1 2026. We would not use those observations to support a straight-line assumption that every coming period will improve.
We first establish whether the quoted return comes from an actual tenancy, an operator statement or a model. Market-wide movement cannot replace the underlying document. Before using a market comparison to justify an offer, we would also check whether it records asking prices or completed transactions. Those are different evidence.
Is Ras Al Khaimah automatically a better income investment than Dubai?
Ras Al Khaimah is not automatically a better income investment than Dubai. We need matched properties, equivalent operating costs and consistent treatment of purchase expenses. Our Ras Al Khaimah versus Dubai rental-yield guide starts that comparison on a firmer basis than setting a RAK forecast against an achieved Dubai return.
Gross rent is often presented as investor profit. Expected capital appreciation may then be added to rent and the total described as a reliable annual yield. We would show those components separately and label any resale assumption as uncertain. Neither presentation gives the buyer a dependable measure of income.
When choosing between the emirates, we test whether the alternative property's evidence is strong enough to justify its total cost. A documented owner statement may deserve more weight than a resort-related narrative. We are not dismissing RAK's prospects. We are preventing those prospects from becoming an undisclosed assumption in the price the buyer pays.
How does a Bay Views full-floor purchase work from budget to registration?
We assess a Bay Views full-floor purchase against the entire cash commitment, indicative long-term income and costs still to be confirmed. Bay Views on Hayat Island, Mina Al Arab, Ras Al Khaimah, is handed over and ready now, sold as one full floor only with full payment: AED 16,200,000 for 9,364 sq ft, Sofia Sands instruction, repriced 23 Oct 2026. Our Bay Views instruction is direct, no agency fee.
For a buyer considering an eventual holiday-let strategy, we would first set aside the purchase consideration. We would then prepare a separate schedule for registration, legal work where required, furnishing and working capital. The asking price is not the complete budget. Nor would we assume that anticipated booking receipts could fund settlement: the buyer must be able to meet that payment.
The floor contains 12 residences, comprising 3 studios, 6 one-bedroom apartments and 3 two-bedroom apartments, Sofia Sands instruction, repriced 23 Oct 2026. The operating plan must match that inventory. We need a furnishing and maintenance budget for the whole floor, rather than a forecast built around an isolated apartment.
What remains after the indicative service charge?
Bay Views has indicative whole-floor annual gross rent of about AED 712,800 and a gross return of about 4.4%, Sofia Sands instruction, rents 20 Jun 2026 and yield on reprice 23 Oct 2026. These are indicative long-term figures, not achieved holiday-let results. Studio rent remains on request, so we would obtain the complete rent schedule before relying on the aggregate.
The indicative service charge is about AED 12/sq ft, Sofia Sands instruction, repriced 23 Oct 2026. Applying that charge to the floor area gives AED 112,368 annually. Deducting it from indicative gross rent leaves AED 600,432, or approximately 3.71% of the purchase price, before all other expenses. We would describe neither result as a net yield.
Before proceeding, we would verify current service-charge statements, arrears and the title, then request the applicable no-objection certificate requirements from the developer's NOC desk. Before remitting completion money, we would confirm registration documents and charges with Ras Al Khaimah Municipality. RAK property is registered there, not with Dubai Land Department (DLD). The buyer must be able to fund the unresolved costs as well as the price.
How much must a holiday let earn to beat long-term rent?
A holiday let must leave the owner more income than long-term letting after its extra operating costs; higher gross revenue is not enough. We would use the long-term case as the comparison and ask the operator to show the receipts needed to beat it. Until we have the contract and cost schedule, we cannot responsibly put an amount on that threshold.
We start with expected long-term collected rent, allowing explicitly for vacancy, maintenance and owner-paid expenses. We then build the holiday-let case from collected accommodation receipts, deducting platform charges, operator fees, utilities, cleaning exposure, consumables and replacement reserves. Common costs need consistent treatment across both strategies. Expenses unique to holiday letting should remain visible rather than disappearing into a general allowance.
We check for double deductions where the platform and operator both refer to an expense in their summaries. The reverse matters too: an expense has not disappeared because the operator pays the invoice before deducting it from the owner's payout.
What evidence would make us choose holiday letting?
We would favour holiday letting where comparable owner accounts show a sufficient surplus after all expenses and the buyer can tolerate uneven receipts. We ask the operator to work backwards: calculate the collected revenue needed to match the long-term alternative, then show which evidenced combinations of occupied nights and realised rates could reach it.
We would test weaker trading against actual softer periods in the operator's accounts, not an invented scenario designed to reassure. The operator should disclose the comparison dates and explain how the comparable accommodation differs from the proposed purchase. A forecast built only on holiday peaks would not change our preference for the more defensible letting strategy.
The exit terms determine whether the fallback is usable. We check notice requirements, responsibility for existing bookings and ownership of furnishings and listing material. Long-term letting is not immediately available if the agreement or accepted reservations prevent a timely change. We would rather accept a less ambitious forecast with a workable exit than a higher projection tied to an inflexible contract.
What must be checked before a RAK apartment accepts paying guests?
We would not underwrite a RAK apartment as a holiday let until its operating permission, building rules and operator responsibilities are confirmed. Ownership does not settle permission to host paying guests. We would ask Ras Al Khaimah Municipality which tourism authority handles the proposed activity, then confirm the current requirements directly with that authority rather than assume permission follows the purchase.
At the building-management desk, we request written guest-access arrangements, occupancy restrictions and the rules for common facilities. We compare those with the operator's sales presentation. If the manager describes a different arrival process or amenity entitlement, we would resolve the discrepancy before the accommodation is advertised.
For a ready property, we inspect its condition and establish who pays to correct defects before guests arrive. We ask the insurer to confirm the proposed use rather than assume ordinary residential cover is sufficient. Emergency attendance also needs checking when the owner lives abroad. An unanswered maintenance call can become a refund and a damaged review.
What should the operator agreement actually say?
The operator agreement should state who can price accommodation, incur expenses, accept bookings and deduct money from the owner's receipts. We request a sample owner statement and trace a booking through to payout. A contract that names a fee without defining its calculation base leaves the central commercial question unanswered, however clear the headline percentage appears.
- Identify the contracting operator and confirm who holds the relevant permissions.
- Define revenue, fee deductions, refund authority and owner reporting access.
- Record spending approvals, maintenance responsibilities and replacement ownership.
- Set payout timing, termination mechanics and treatment of bookings after notice.
We also check whether comparable statements include every owner-paid expense. Where electricity or repairs sit outside them, we add the invoices to the model. Taking the operator's fee off revenue does not make the remainder net income. A useful forecast must reconcile to the owner's entire property account, including bills paid elsewhere.
How does RAK compare with London and Singapore for an overseas buyer?
We compare RAK with London and Singapore by separating acquisition taxes and ongoing ownership costs from rental yield. The UAE has no annual property tax and no capital gains tax on individuals, UAE Federal Tax Authority VAT guidance; UAE tax framework, checked 29 Oct 2026. We would verify the buyer's intended ownership and letting arrangement before applying that statement. It does not mean every activity is tax-free.
Residential property sales are exempt from VAT, with qualifying first sales of new homes zero-rated, UAE Federal Tax Authority (FTA) VAT guidance; UAE tax framework, checked 29 Oct 2026. We would not extend that residential-sale treatment to every holiday-accommodation service. A qualified adviser should review the proposed activity and invoicing arrangements before the buyer relies on a tax assumption.
Which overseas purchase-tax comparisons need verification?
Overseas purchase-tax comparisons need an individual check of the buyer's circumstances. For London buyers, the additional-home Stamp Duty surcharge is 5% and the non-UK-resident surcharge is a further 2%, HMRC SDLT guidance as summarised by UK tax calculators, checked 29 Oct 2026; confirm with His Majesty's Revenue and Customs (HMRC). We would verify eligibility and residence rather than apply a blanket assumption.
Singapore's foreign-buyer Additional Buyer's Stamp Duty (ABSD) is reported as 60%, IRAS ABSD schedule as reported by Singapore property portals, checked 29 Oct 2026; confirm with the Inland Revenue Authority of Singapore (IRAS). Nationality-related treaty exceptions mean the buyer's passport can change the comparison. We would obtain an individual tax calculation before using the headline charge to favour another market.
What changes when the RAK buyer lives abroad?
Living abroad adds separate checks for borrowing, immigration, remote signing and fund transfers; the rental model answers none of them. We would ask the bank to confirm non-resident loan-to-value and how its valuer will assess the property. The asking price cannot stand in for the bank's lending basis.
We would confirm visa status and any Golden Visa or Green Visa eligibility with the Federal Authority for Identity, Citizenship, Customs and Port Security (ICP). For remote signing, the receiving registration authority should confirm the required power of attorney and authentication. We would ask the remitting and receiving banks about source-of-funds documents, currency conversion and settlement timing, and ask the Central Bank of the UAE (CBUAE) to confirm the AED's US-dollar peg when assessing currency exposure. These checks do not imply eligibility. Home-country tax requires a local adviser; we give no home-country tax advice.
What would make us proceed, renegotiate or walk away?
We would proceed near Wynn only when the price works against a documented fallback and the holiday-let case survives a complete expense review. The resort's potential demand gives us a reason to investigate, not a reason to relax purchase discipline. If the income evidence is weak, we would change the price or strategy rather than make the forecast more flattering.
Before an unconditional commitment, we would assemble title checks, current building charges, operating permissions and a reconciled rental model in a decision file. We would ask the seller or developer to clarify unresolved costs in writing. At the NOC desk, we identify outstanding requirements while there is time to address them. A missing document should not first come to light when funds are ready to move.
We would not use Dubai trustee-office procedures as a template for a RAK transfer. We confirm the actual appointment, signing and payment requirements with Ras Al Khaimah Municipality and the parties handling the transaction.
What is the final investment checklist?
A purchase is ready for a decision when every income assumption has an evidence source and responsibility for each material cost is clear. Before treating the rental model as a purchase recommendation, we would work through these checks and record the answers.
- Label every income line as achieved, indicative or forecast, with the relevant period.
- Separate purchase consideration from registration, establishment costs and working capital.
- Compare holiday letting with a documented long-term alternative on consistent terms.
- Verify building access and operating permission before paying for guest-specific furnishing.
- Confirm the owner's ability to carry the property through weak trading or an opening delay.
- Record what evidence would trigger a change of strategy or a revised offer.
Our default remains long-term underwriting first. Credible operator accounts showing an adequate additional return for the work, uncertainty and capital involved would make us reconsider. Until then, an empty occupancy cell records an honest limitation. Filling it with an attractive percentage would make the model easier to sell, but less useful to the buyer deciding whether to commit.
What to take away
- No achieved Wynn post-opening rental yield exists before opening.
- Long-term rent is a comparison baseline, not a guaranteed income floor.
- Bay Views is ready now and sold as one full floor only, with full payment.
- Deduct every owner-paid expense before describing a return as net.
- Confirm guest permissions and the operator's exit terms before furnishing.
- Sofia Sands direct instructions are direct, no agency fee.
Questions buyers ask
Can an operator guarantee the rental yield near Wynn?
A forecast is not a guarantee. For a Ras Al Khaimah property near Wynn, ask whether any promised payment is a contractual obligation, who owes it and what exclusions apply. Have the agreement reviewed before relying on that income. Existing operating accounts can support current-market analysis, but they cannot demonstrate achieved performance after a resort opening that has not yet occurred.
When is Wynn Al Marjan Island scheduled to open?
Wynn Al Marjan Island is scheduled to open in September 2027, Wynn Resorts SEC filing / earnings release, 4 Aug 2026. Buyers should monitor Wynn Resorts updates rather than treating an advertised timetable as a rental guarantee. The property model should remain workable if guest demand develops differently from the operator's forecast or income takes longer to establish.
Is the Bay Views gross return a holiday-let forecast?
No. Bay Views has an indicative whole-floor gross return of about 4.4%, Sofia Sands instruction, rents 20 Jun 2026 and yield on reprice 23 Oct 2026. That is a long-term rental reference, before operating expenses, not an achieved holiday-let result. Bay Views is handed over and ready now, sold as one full floor only with full payment.
Does no annual property tax mean the rental return is tax-free?
No annual property tax does not mean there are no operating expenses or other tax questions. The UAE has no annual property tax and no capital gains tax on individuals, UAE Federal Tax Authority VAT guidance; UAE tax framework, checked 29 Oct 2026. Holiday-accommodation activity and the buyer's ownership arrangement need their own review. Overseas buyers should confirm home-country tax with a local adviser.
Is a studio automatically the highest-yielding choice?
No apartment type automatically produces the strongest Ras Al Khaimah return. Compare the complete acquisition and furnishing cost with evidenced owner income for genuinely comparable accommodation. Check permitted guest capacity, cleaning exposure and replacement costs. A building-wide average cannot establish whether a particular studio or larger apartment will outperform after expenses.
Can a non-resident buy remotely and use a mortgage?
A non-resident should obtain written confirmation of borrowing eligibility and loan-to-value from the bank, and remote-signing requirements from Ras Al Khaimah Municipality. Confirm the power of attorney and authentication process before arranging a signing appointment. Visa eligibility is a separate question for the Federal Authority for Identity, Citizenship, Customs and Port Security (ICP); do not assume a purchase settles immigration status.
Want projects that fit this, with price lists?
Sofia Sands Realty · RERA 41793 · Sofia replies on WhatsApp, usually within minutes
Sources, dated
- Wynn Resorts SEC filing / earnings release, 4 Aug 2026
- Cavendish Maxwell H1 2026
- Sofia Sands instruction, repriced 23 Oct 2026
- Sofia Sands instruction (rents 20 Jun 2026; yield on 16.2M reprice 23 Oct 2026)
- UAE Federal Tax Authority VAT guidance; UAE tax framework, checked 29 Oct 2026
- HMRC SDLT guidance as summarised by UK tax calculators, checked 29 Oct 2026
- IRAS ABSD schedule as reported by Singapore property portals, checked 29 Oct 2026
How this guide was made. Researched against dated primary sources (Dubai Land Department, Central Bank of the UAE, Ras Al Khaimah Municipality, developer and operator filings) and against the pages currently ranking for this question. Drafted with AI assistance under Yitayal Mesfin's editorial rules; every figure is machine-checked against our fact register and the draft is scored by a review panel before it goes live. Figures checked 12 November 2026. Figures use the dated checks cited from June through October 2026; revised resort guidance, current rental evidence, building charges, operator contracts and authority rules could change the underwriting.
Further reading
- Rental Yield: Ras Al Khaimah vs Dubai (2026 Numbers)
- Wynn Al Marjan Island Construction Progress (Nov 2026 Update)
- Bay Views, Hayat Island — one full floor, twelve residences
- Why invest in Ras Al Khaimah — the Wynn window and the ready alternative
- Selling in Ras Al Khaimah: Who Sets Your Price (2026)
- Non-Resident Mortgages in Dubai and RAK (2026): LTV, Banks
- Al Marjan Island Capital Growth to 2027: A Realistic Range
- Golden Visa via Property: RAK vs Dubai Rules (2026)